Paystub Basics
Direct Deposit Paystubs Without a Physical Check: What They Show
What a paystub shows when pay goes straight to a bank account, how split deposits add up to net pay, and the few cases where a check number still belongs.
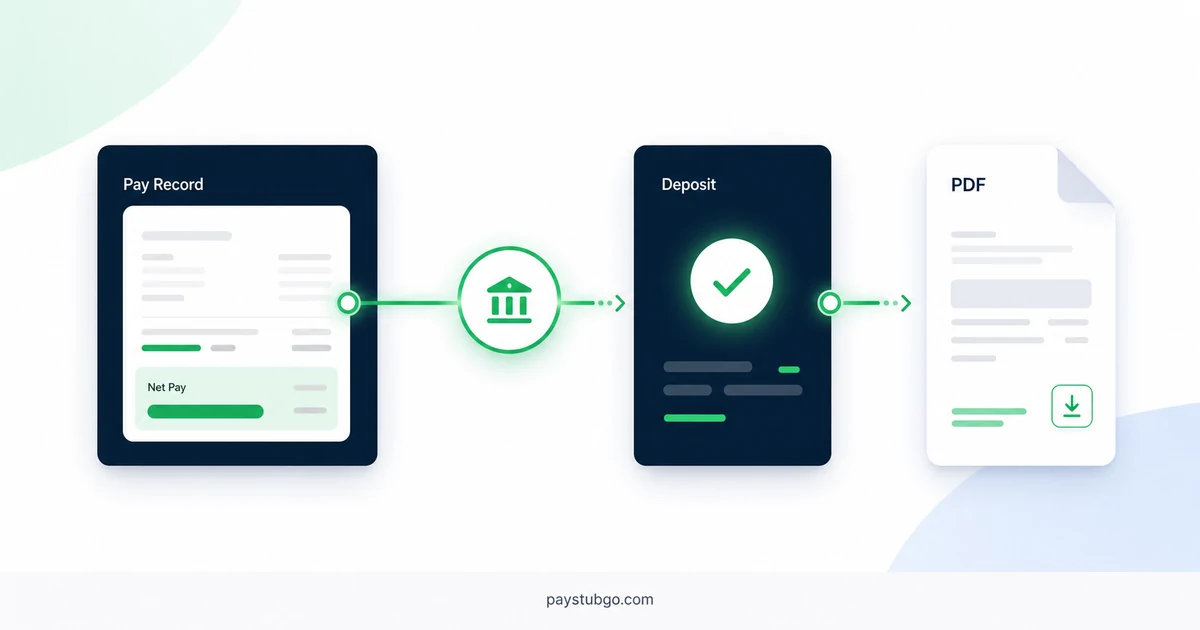
Table of Contents
What this guide covers
6 sectionsHide
Table of Contents
What this guide covers
Scroll inside this box to view all guide topics.
A direct deposit paystub records a payment that went to a bank account, so there is no check to detach. It should show gross pay, deductions and net pay, plus each deposit amount, the account it went to, masked to the last four digits, and the pay date. A check number belongs only when a paper check was issued.
Older stubs were the tear-off half of a paycheck, which is why many people still expect a check number, a memo line or a "void" watermark. With direct deposit the stub stands alone as a statement. Knowing what replaced the check makes it easier to read one and to prepare one correctly.
How a direct deposit statement differs from a check stub
Most lines are the same on both: the employer and employee details, the period, earnings, deductions and year-to-date totals. The differences sit around how the net pay left the business.
| Element | Paper check stub | Direct deposit statement |
|---|---|---|
| Payment instrument | A check attached or issued with it | None; an electronic transfer |
| Check number | Printed, matching the check | Blank, or not shown at all |
| Net pay | The amount of the check | The total of all deposits |
| Account details | Not needed | Each receiving account, masked to the last four digits |
| Wording on the document | Often includes the payable check itself | Often marked as a statement or "non-negotiable" |
The last row is a common convention rather than a rule: printing "non-negotiable" or "this is not a check" makes it plain the page cannot be cashed. Everything above net pay reads exactly as it would on a check stub, and the walkthrough on how net pay is reached applies to both formats. People who use the terms interchangeably may also want the short piece on check stubs versus pay stubs.
Related: How to Read a Pay Stub, Line by Line
Related: Can You File Taxes With Your Last Pay Stub? Form 4852 Explained
When a check number should appear on a stub
A check number is a reference to a physical check in the employer's check register. It belongs on a stub when, and only when, that stub describes a payment made by paper check. Typical cases:
- Regular payroll by check, for employees who have not set up direct deposit.
- An off-cycle manual check, such as a missed overtime payment issued between regular paydays.
- A final paycheck handed over on the last day, when the business pays final wages by check.
- A replacement check for one that was lost or voided, where the new number should appear and the old one should be noted as void in the register.
If the payment went by direct deposit, leave the check number field empty. A made-up number on a deposit stub points to a check that does not exist, which will confuse anyone reconciling the bank account and makes the document inaccurate.
Illustrative example (made-up figures): An employee is normally paid by direct deposit. On the April 24, 2026 payday the regular stub shows net pay of $1,612.40 deposited to checking ending 4821, with no check number. Two days later the employer discovers 3 overtime hours at $31.50 were missed, a gross of $94.50, and hands the employee a manual check, number 5117, for the net amount after withholding. That off-cycle stub shows check number 5117, while the April 24 deposit stub stays exactly as it was.
Switching from paper checks to direct deposit midyear
When an employee moves from checks to direct deposit partway through the year, the first deposit stub deserves a second look. Confirm the money went to the account named on the signed authorization, that no paper check was also cut for the same pay date, and that year-to-date totals continue from the last check stub instead of restarting at zero. From that stub onward the check number field stays empty, unless a manual check is issued again for a one-off payment.
Split deposits and the net pay line
Many employees send part of their pay to a second account. The stub should then list each deposit separately, and the deposits must add up to net pay exactly. A common setup sends a fixed amount to one account and the remainder to another.
Illustrative example (made-up figures): A biweekly employee's net pay is $1,850.00. Their deposit instructions send a fixed $350.00 to savings ending 0937 and the balance to checking ending 4821. The stub lists two deposit lines: $350.00 to account ending 0937 and $1,850.00 − $350.00 = $1,500.00 to account ending 4821. Added together, $350.00 + $1,500.00 = $1,850.00, which matches net pay. If a pay period ever produced net pay below $350, the stub should show how the fixed amount was handled rather than a savings deposit larger than the total.
Mask account numbers to the last four digits on every stub. The full account and routing numbers belong only in the direct deposit authorization kept in the restricted payroll file.
Matching the stub to the bank statement
With no check to cash, the bank statement becomes the proof that pay arrived. A quick match each payday catches most problems:
- Find the deposit dated on or near the pay date shown on the stub.
- Confirm the amount equals the deposit line for that account, not the gross pay.
- For split deposits, find the matching amount in each account.
- Expect the name on the bank line to differ sometimes, since a payroll provider may send the transfer under its own name.
The pay date on the stub is the day wages are paid, which can be several days after the period ends; the difference is explained in pay date and period end date. A deposit that appears a day before or after the pay date is usually a matter of bank processing, but a deposit that is missing or for a different amount is a question for payroll.
Can an employer require direct deposit?
The federal rule on this comes from Regulation E, which the Consumer Financial Protection Bureau administers. Section 1005.10(e)(2) says no financial institution or other person may require a consumer to establish an account for receipt of electronic fund transfers with a particular institution as a condition of employment. The official interpretation adds that an employer may require direct deposit if employees can choose the institution, or may offer a choice between an institution the employer designates and another method such as a check or cash.
States can add their own conditions on how wages are paid, including consent requirements for direct deposit or pay cards, so the federal rule is not the whole picture. Your state labor department publishes the payment-method rules that apply to your employees.
Delivering the stub when there is no envelope
A paper check came with its stub. Direct deposit does not, so the business needs a separate way to deliver statements, and federal wage law does not require a stub at all; the obligation, where it exists, comes from state law. Some states set conditions for electronic delivery. Washington's WAC 296-126-040, for instance, allows electronic statements if employees can access and copy them on payday, and requires a written statement for an employee who cannot.
Whatever the channel, the stub should reach the employee by the pay date and include every item your state lists. The overview of standard pay stub fields covers the core set.
If you prepare statements yourself, you can create a paycheck stub in PayStubGo from your payroll figures, enter the deposit details as they were actually paid, and leave the check number blank for deposit payments. PayStubGo formats and previews the information you provide; it does not move money, confirm a deposit or verify any amount, and it does not replace your payroll provider or legal guidance on how wages must be paid.
PayStubGo
Create a paystub from your own details
Preview your paystub, review the layout, and download a clean PDF when the information looks right.