Paystub Basics
Overtime Pay on a Pay Stub: Regular vs Overtime Lines
Regular and overtime lines explained with worked arithmetic, the FLSA regular rate, and the qualified overtime amount employers report with W-2 code TT.
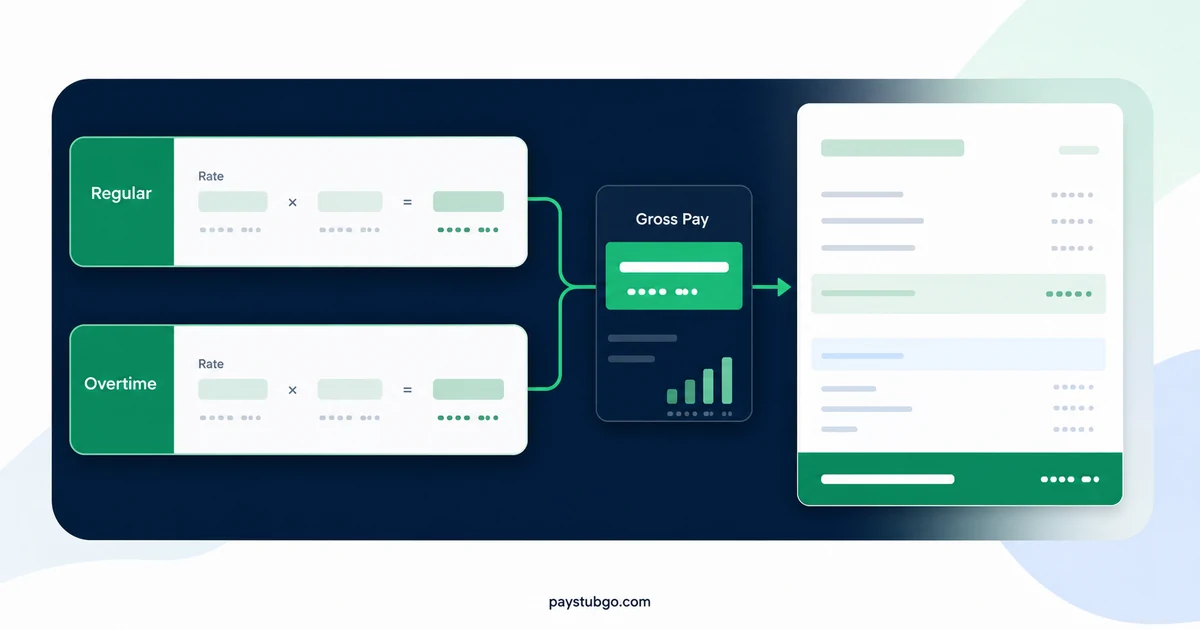
Table of Contents
What this guide covers
8 sectionsHide
Table of Contents
What this guide covers
Scroll inside this box to view all guide topics.
- What turns an hour into overtime
- How the two lines look on a stub
- Working out a 46-hour week
- When the regular rate is higher than the hourly rate
- Qualified overtime and W-2 Box 12 code TT
- From YTD overtime to the code TT figure
- Checking regular and overtime lines on your stub
- Recording regular and overtime pay on a paystub record
Regular pay covers hours up to the overtime threshold at the employee's normal rate; overtime pay covers hours beyond it at a higher rate. Under federal law that means hours over 40 in a workweek, paid at least 1.5 times the regular rate, so a stub shows overtime as its own line of hours × rate × 1.5.
Overtime also has a new job at year end. Starting with 2026 Forms W-2, employers report the qualified overtime premium in Box 12 with code TT, which connects to a federal deduction created by a 2025 law. The sections below show how the two pay lines are built, work the arithmetic with made-up figures, and set out what employers report and what employees do with it. For the other parts of the stub, see the guide to the parts of a pay stub.
What turns an hour into overtime
Department of Labor Fact Sheet #23, last revised in October 2019, sets out the federal rule under the Fair Labor Standards Act (FLSA). Unless an employee is exempt, every hour worked beyond 40 in a workweek must be paid at no less than one and one-half times the regular rate. Four details from that fact sheet shape what appears on a stub:
- The workweek is fixed. It is a recurring block of 168 hours, seven consecutive 24-hour periods, and can start on any day the employer chooses.
- Weeks stand alone. Hours cannot be averaged across two or more weeks, so a 50-hour week followed by a 30-hour week still produces 10 overtime hours.
- Weekends and holidays are not overtime by themselves. Saturday, Sunday or holiday work only earns an overtime premium under federal law when it pushes the week past 40 hours.
- Exempt employees are outside the rule. Many salaried executive, administrative and professional employees receive no overtime line at all.
States can add their own thresholds on top of the federal one. California, for example, also counts hours worked beyond a daily limit, so a stub for work there can show overtime in a week with fewer than 40 hours. The paystub generator for California covers the state's wage statement details.
How the two lines look on a stub
A typical hourly stub puts regular and overtime pay on separate rows, each with its own hours and rate:
| Line | Hours | Rate | Amount |
|---|---|---|---|
| REG | 40.00 | $18.00 | $720.00 |
| OT | 6.00 | $27.00 | $162.00 |
| Gross pay | 46.00 | $882.00 |
A second layout pays all hours at the base rate and adds only the extra half as an "OT premium" line. Both layouts produce the same gross pay, and the next section shows why.
Working out a 46-hour week
Illustrative example (made-up figures): an hourly employee earning $18.00 an hour works 46 hours in one workweek, with no bonuses or commissions.
- Regular pay: 40 hours × $18.00 = $720.00
- Overtime hours: 46 − 40 = 6
- Overtime rate: $18.00 × 1.5 = $27.00
- Overtime pay: 6 hours × $27.00 = $162.00
- Gross pay: $720.00 + $162.00 = $882.00
The $162.00 of overtime pay has two parts. The straight-time portion, 6 × $18.00 = $108.00, is what those hours would earn at the normal rate. The premium portion, 6 × $9.00 = $54.00, is the extra half. A premium-style stub shows "REG 46.00 × $18.00 = $828.00" and "OT premium 6.00 × $9.00 = $54.00", which is also $882.00.
That split matters more than it used to, because the premium portion is the part the IRS calls qualified overtime compensation.
When the regular rate is higher than the hourly rate
The "regular rate" in the overtime rule is not always the posted hourly rate. Fact Sheet #23 says it includes all remuneration for employment except payments the law itself excludes, and it names commissions as included. Department of Labor Fact Sheet #56C (revised December 2019) adds that nondiscretionary bonuses, such as production, attendance, safety or quality bonuses, must be included too. When an employee works at two different rates in one week, the fact sheet describes the regular rate as the weighted average of those rates.
Illustrative example (made-up figures): an hourly employee paid $20.00 an hour works 45 hours in a week and earns a $90.00 production bonus for that same week.
- Straight-time pay for all hours: 45 × $20.00 = $900.00
- Add the bonus: $900.00 + $90.00 = $990.00
- Regular rate: $990.00 ÷ 45 = $22.00
- Overtime premium: 5 hours × half of $22.00, or 5 × $11.00 = $55.00
- Total pay for the week: $990.00 + $55.00 = $1,045.00
Calculating overtime from the hourly rate alone would give 40 × $20.00 + 5 × $30.00 + $90.00 = $1,040.00, which is $5.00 short. On a stub, that difference often appears as a separate "OT adjustment" line, sometimes on a later paycheck once the bonus has been calculated.
Qualified overtime and W-2 Box 12 code TT
What the 2025 law created
Public Law 119-21, enacted in 2025, created a federal income tax deduction for qualified overtime compensation for tax years 2025 through 2028. IRS questions and answers on the deduction (fact sheet FS-2026-13, updated August 6, 2026) describe its main terms:
- Qualified overtime compensation is overtime pay required under section 7 of the FLSA that exceeds the regular rate, which in practice is the premium portion.
- Overtime paid only because of a state law, a collective bargaining agreement or company policy does not qualify, and an employee who is not eligible for FLSA overtime does not receive qualified overtime compensation.
- The deduction is up to $12,500 per return, or $25,000 on a joint return.
- It is reduced when modified adjusted gross income exceeds $150,000, or $300,000 for joint filers.
- The employee needs a Social Security number valid for employment, and a married employee must file jointly to claim it.
What employers report
For tax year 2025, employers were not required to report qualified overtime separately. IRS Notice 2025-62, announced on November 5, 2025, confirmed that 2025 Forms W-2 would not change and encouraged employers to share the amount another way, such as in Box 14 of Form W-2, an additional written statement or an online portal.
For 2026 and later, separate reporting is required. The IRS General Instructions for Forms W-2 and W-3 (2026) add Box 12 code TT for the total amount of qualified overtime compensation, and 2026 Forms W-2 are due to employees by February 1, 2027. The instructions also make clear that code TT shows the full qualified amount paid, not the deductible amount. Their example: an employer that paid $30,000 of qualified overtime compensation in 2026 reports $30,000 with code TT, even though the deduction is capped at $12,500.
What the employee does with it
The deduction is figured on the employee's own federal return, where the limits and income reduction apply. The Box 12 code TT amount is a starting figure for that calculation, not a result. For 2025, when many employers did not report the amount, the IRS allows individuals to use the methods in Notice 2025-69 and the Schedule 1-A instructions to work it out.
Two things do not change on the paystub. IRS Publication 15 (2026) says overtime remains subject to Social Security and Medicare for both the employee and employer shares, and income tax withholding still follows the employee's Form W-4. Publication 15 notes that an employee may use an updated W-4 to account for an expected deduction.
| Question | Employer, on Form W-2 | Employee, on their return |
|---|---|---|
| Which amount? | Total qualified overtime premium paid | Deduction up to the limit |
| Limits applied? | No | Yes, $12,500 or $25,000, reduced at higher income |
| Tax year 2025 | Separate reporting optional | May figure the amount using IRS methods |
| Tax year 2026 | Box 12 code TT required | Starts from the code TT amount |
| Social Security and Medicare | Still withheld | Not affected by the deduction |
From YTD overtime to the code TT figure
Illustrative example (made-up figures): an hourly employee's regular rate stays at $24.00 all year, and all of their overtime is required by the FLSA. By the final stub of 2026 they have worked 300 overtime hours.
- YTD overtime pay: 300 hours × $36.00 = $10,800.00
- Straight-time portion: 300 × $24.00 = $7,200.00
- Premium portion: 300 × $12.00 = $3,600.00
The $3,600.00 premium is the amount that would appear with code TT, not the $10,800.00 shown on the overtime line. When overtime is always paid at exactly 1.5 times a constant regular rate, the premium is one third of total overtime pay, and $10,800.00 ÷ 3 = $3,600.00 confirms it.
That shortcut stops working when the regular rate changes during the year, when bonuses or commissions raise the rate for particular weeks, or when the overtime line includes double time or state-only overtime. In those cases the employer's code TT figure is the one to use, and it is reasonable to ask payroll how it was calculated.
Checking regular and overtime lines on your stub
- Add the hours from each workweek separately, using the timesheet, and confirm any hours above 40 in a week appear as overtime.
- Multiply regular hours by the base rate and compare with the regular line.
- Check that the overtime rate is at least 1.5 times the regular rate, including any bonus or commission for that week.
- Look for an "OT adjustment" line when a nondiscretionary bonus was paid.
- Confirm that regular and overtime amounts add up to gross pay along with any other earnings.
- Watch the YTD overtime line, since it will be the base for the 2026 code TT amount.
The way overtime flows through to take-home pay is covered in gross and net pay, and the running totals that feed year-end forms are explained in YTD on a paystub. If a bonus caused the overtime adjustment, bonus withholding methods explain why that line may be taxed differently.
Related: Tips on a Pay Stub: Reported Tips and the Tip Credit
Recording regular and overtime pay on a paystub record
On PayStubGo's online paystub generator, regular hours and the hourly rate go in their own fields, and overtime has separate hours and rate fields. The form multiplies overtime hours by the overtime rate you enter, so type the dollar rate, such as $27.00, rather than a multiplier such as 1.5. If the source stub shows an overtime adjustment or a premium-only line, compare the preview with it so the gross pay matches.
This article explains how overtime appears on paystubs and forms; it is not tax advice. Whether and how much of the qualified overtime deduction applies to a particular return is a question for the IRS guidance itself or a tax professional, and PayStubGo does not calculate overtime eligibility or tax amounts.
PayStubGo
Create a paystub from your own details
Preview your paystub, review the layout, and download a clean PDF when the information looks right.